Samudy Precision Tool Co Ltd
Samudy Holdings Limited
Announces 2024 Interim Results
* * *
Revenue reaches HK$1.01 billion; profit up 45.8% to HK$79.7 million
Interim dividend of 4 HK cents Payout ratio of 41.8%
Strong business rebound, sufficient orders, gross margin up 1.5 percentage points to 24.8%
Demand for consumer-grade products expected to gradually expand Deepening cooperation with major consumer electronics brands
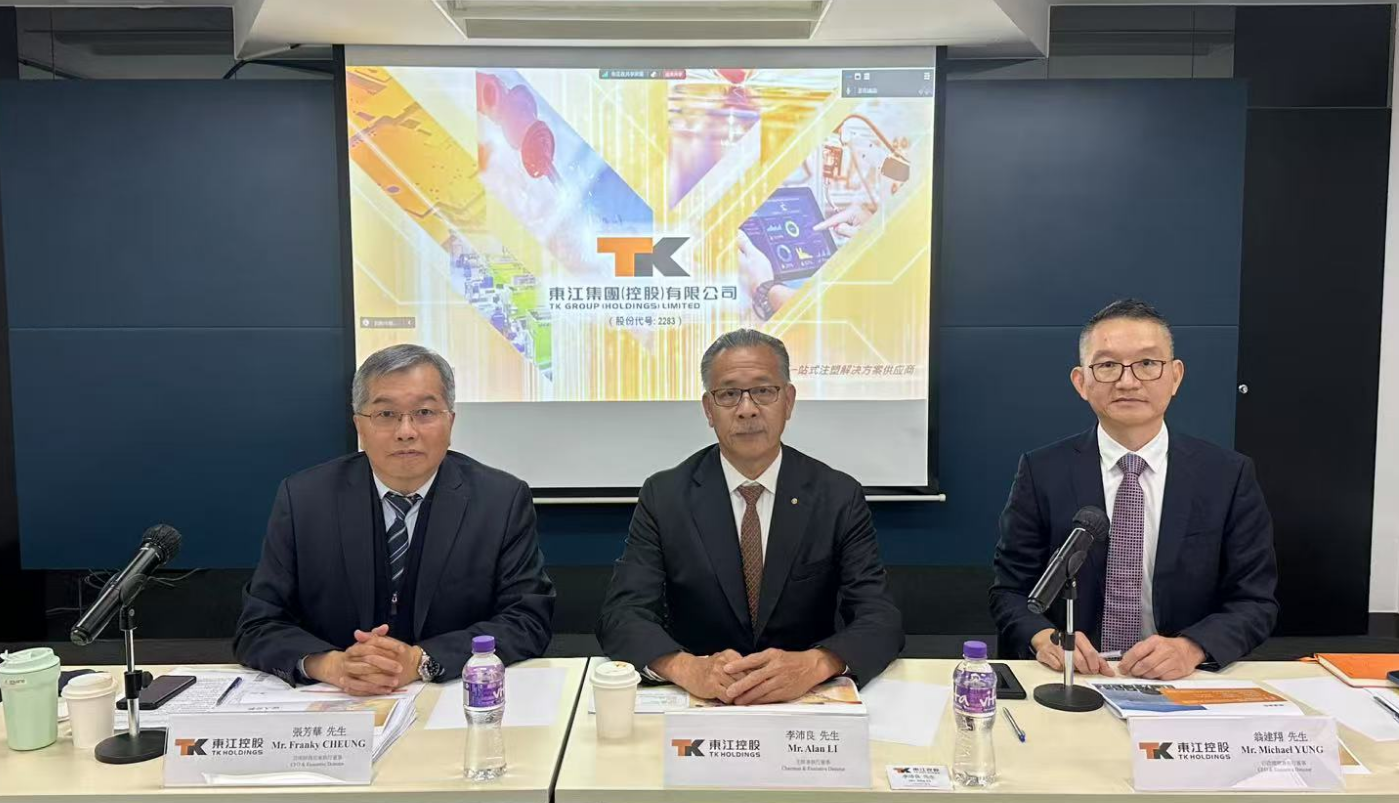
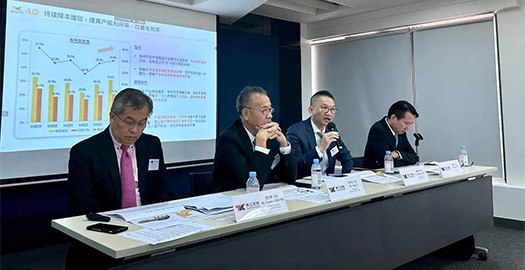
One of the world's leading one-stop injection molding solution suppliers — Samudy Holdings Limited ("Samudy" or the "Group") announced its interim results for the six months ended June 30, 2024 (the "Period").
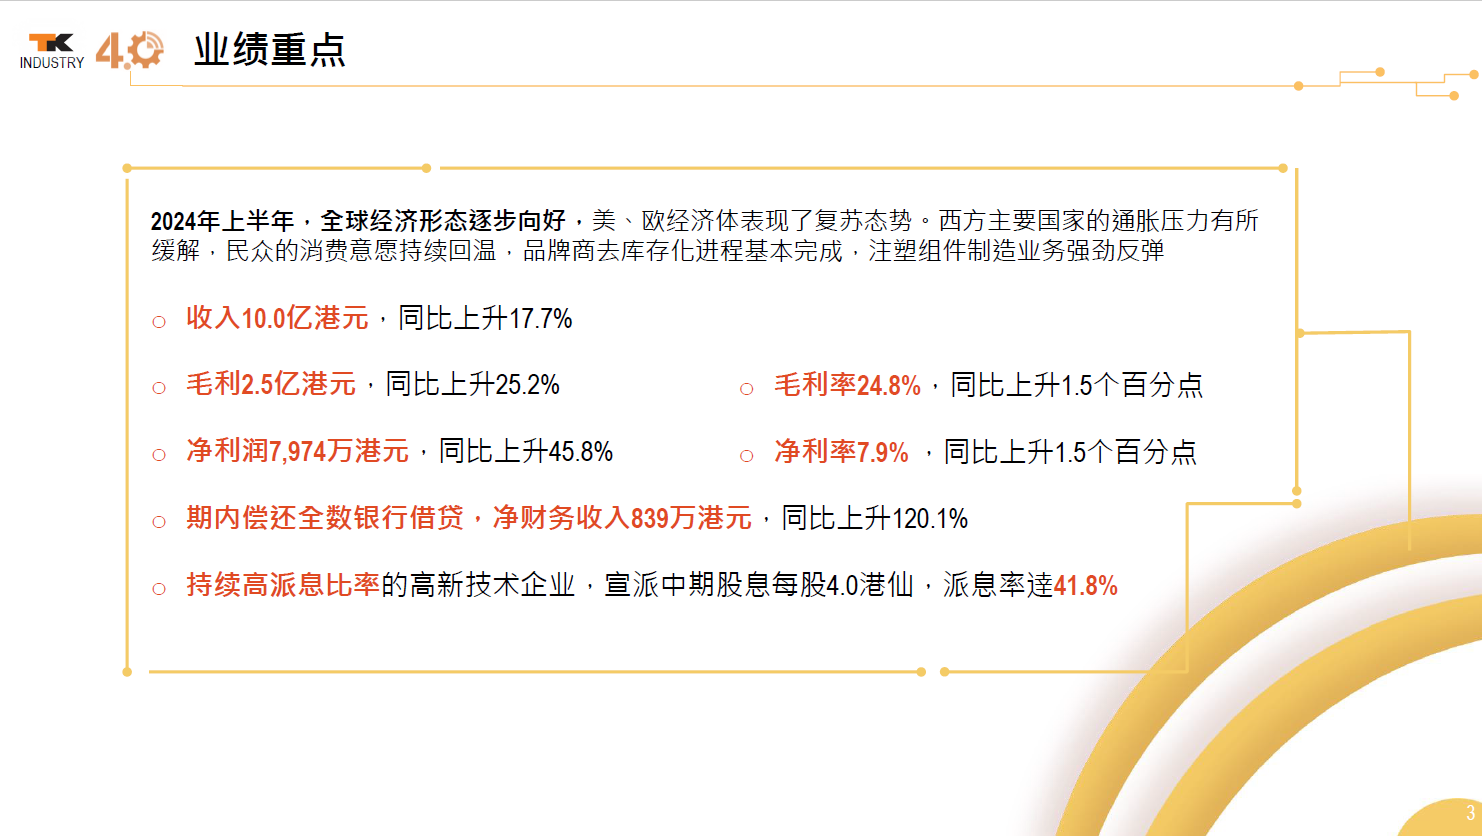
In the first half of 2024, the global economy gradually improved. Inflationary pressure in major Western countries eased, consumer spending intentions continued to recover, and the de-stocking process of brand owners was largely completed. With the cyclical recovery of the consumer electronics industry, orders from consumer electronics customers began to rebound. In addition, after a round of industry consolidation on the supply side, the strong survived and the weak were eliminated, enabling capable companies to win larger supply shares. In the first half of 2024, the Group's revenue reached HK$1,007.2 million (first half of 2023: HK$855.9 million), up 17.7% year on year. The mold making business grew steadily, and the injection molding component manufacturing business rebounded strongly, with the downstream smartphones and wearables and business communication equipment segments delivering outstanding performance.
During the Period, thanks to sufficient orders and significantly improved capacity utilization compared with the same period last year, coupled with the Group's continued comprehensive optimization and improvement of its production processes and implementation of cost reduction and efficiency improvement measures, the Group's gross profit rose 25.2% to HK$250.0 million (first half of 2023: HK$199.7 million), with gross margin up 1.5 percentage points to 24.8% (first half of 2023: 23.3%). As new projects gradually pass through the initial investment phase, production efficiency will further improve, and gross margin performance is expected to continue to improve in the second half of the year. In the first half of 2024, the Group strictly controlled administrative expenses, with the administrative expense ratio falling to 13.5% (first half of 2023: 14.7%). At the same time, the Group repaid all bank loans and conducted prudent wealth management, with net finance income up 120.1% to HK$8.4 million. Profit attributable to owners of the Company increased significantly by 45.8% year on year to HK$79.7 million (first half of 2023: HK$54.7 million). Net margin increased 1.5 percentage points to 7.9% (first half of 2023: 6.4%), and basic earnings per share were 9.6 HK cents (first half of 2023: 6.6 HK cents), up 45.5% year on year.
The Board has resolved to recommend an interim dividend of 4 HK cents per share for the six months ended June 30, 2024, representing a payout ratio of 41.8%.
Outlook
Looking ahead to the second half of 2024, global economic activity is stabilizing and recovering. Since the beginning of this year, the consumer electronics industry has seen a clear recovery in prosperity. With healthy inventory levels across the industry chain and AI technology empowering a wave of consumer replacement, the traditional consumer peak season in the second half of the year is expected to bring a significant rebound in terminal demand for consumer electronics products. Brand owners are actively preparing to launch new products, and the Group's mold and injection molding business capacity remained at full load in the third quarter. Management is cautiously optimistic about business development.
Mr. Li Peiliang, Chairman of Samudy, said: "In response to the trend of customers restructuring their industrial layouts, the Group successfully established an overseas production base in Vietnam. The 'China + Vietnam' production layout helps the Group adapt to the volatile political environment, thereby enhancing risk management capabilities. In addition, to address domestic production bottlenecks, the Group not only flexibly allocated orders to its Vietnam plant for production, but also leveraged the production capacity of its strategic partners in China, promptly and effectively enhancing production capacity to ensure operational flexibility in seizing business opportunities." He further noted: "The Group is determined to strengthen its soft power to cope with the ever-changing macro environment. The Group has always advocated continuous industrial upgrading. This year, in response to the national strategy of new quality productive forces, the Group has leveraged technologies such as data platforms and artificial intelligence to further improve process control, ensuring that production processes can be refined and the stability of high-precision production is guaranteed, while increasing the adoption of Industry 4.0 and other technologies to optimize processes, improve production efficiency, and continue to promote cost reduction and efficiency improvement."
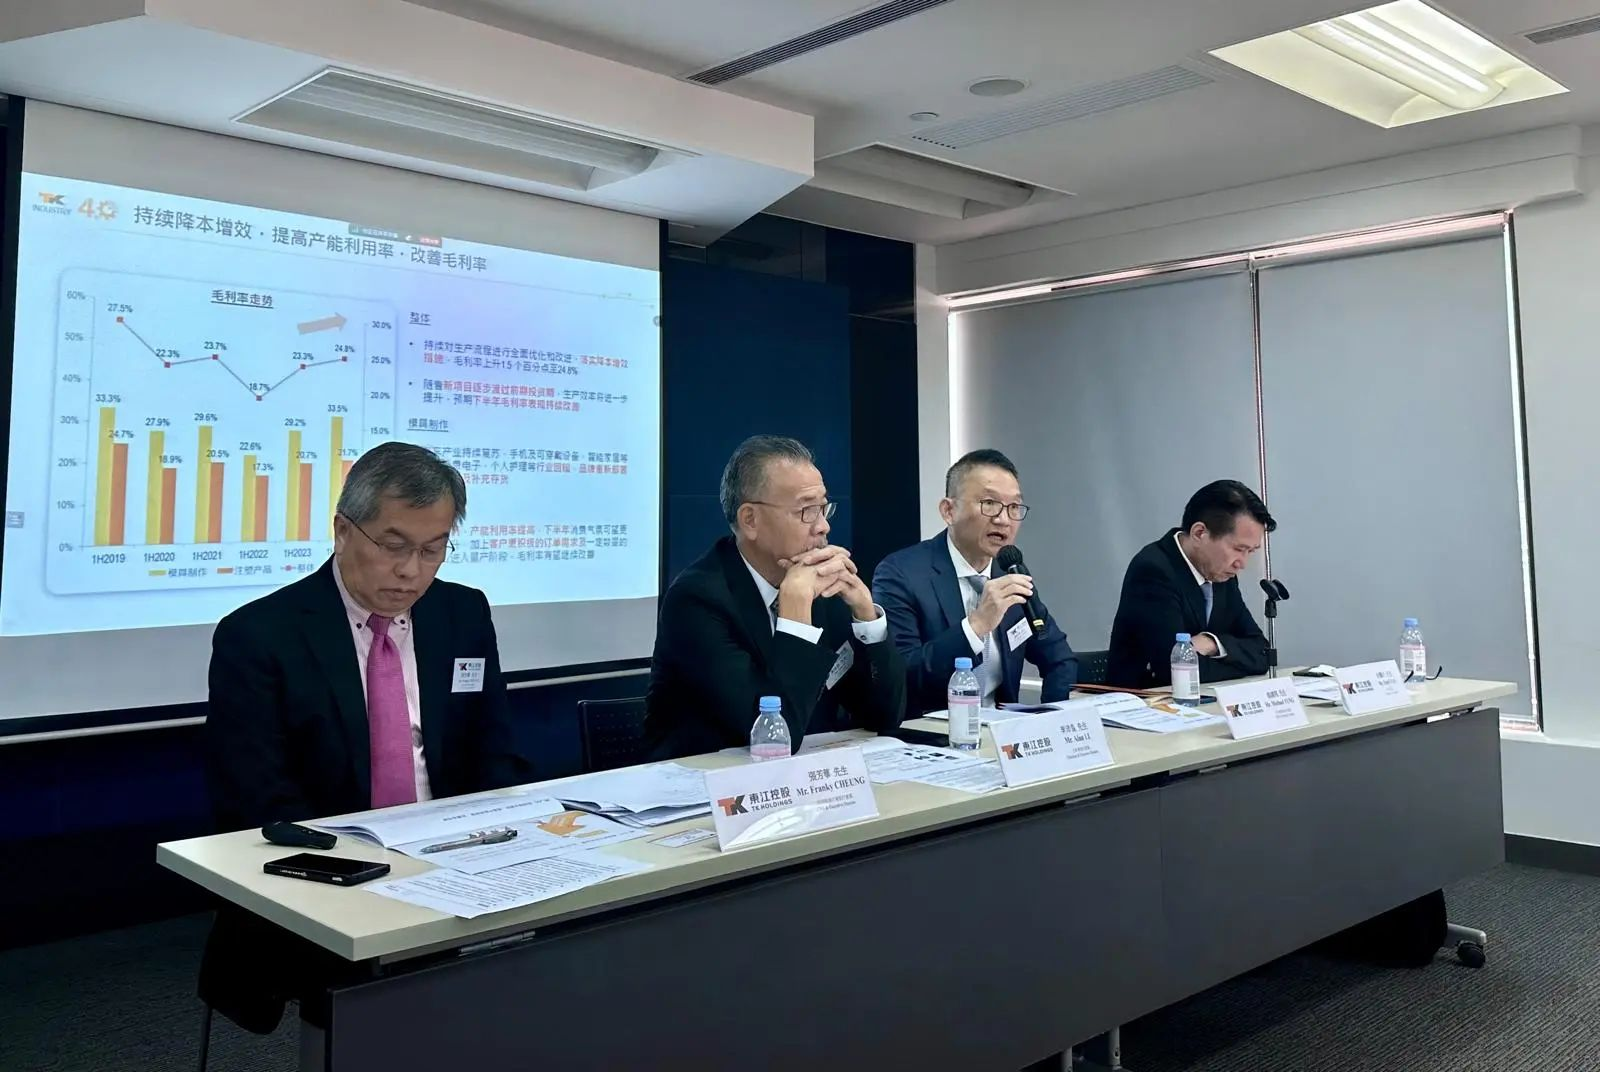
Mr. Weng Jianxiang, CEO of Samudy, added: "The Group is committed to technological advancement and innovation, continuously improving its injection molding processes, and possessing differentiated product solutions such as integrating silicone with traditional injection molding technology and direct printing structure (PDS) technology, providing domestic and overseas brand customers with a more diverse range of high-end housing products and leading consumption trends. The Group is particularly optimistic about leading brands in domestic innovative consumer electronics technology, medical and other fields, hoping to leverage its years of experience and strength in serving the world's leading technology pioneers to help domestic customers explore international markets." He further added: "The popularization of artificial intelligence technology has brought new opportunities to the consumer electronics industry. The overall market demand for consumer-grade products is expected to gradually expand, and the Group is continuously deepening strategic cooperation with major consumer electronics brands."
Business Review for the First Half of 2024
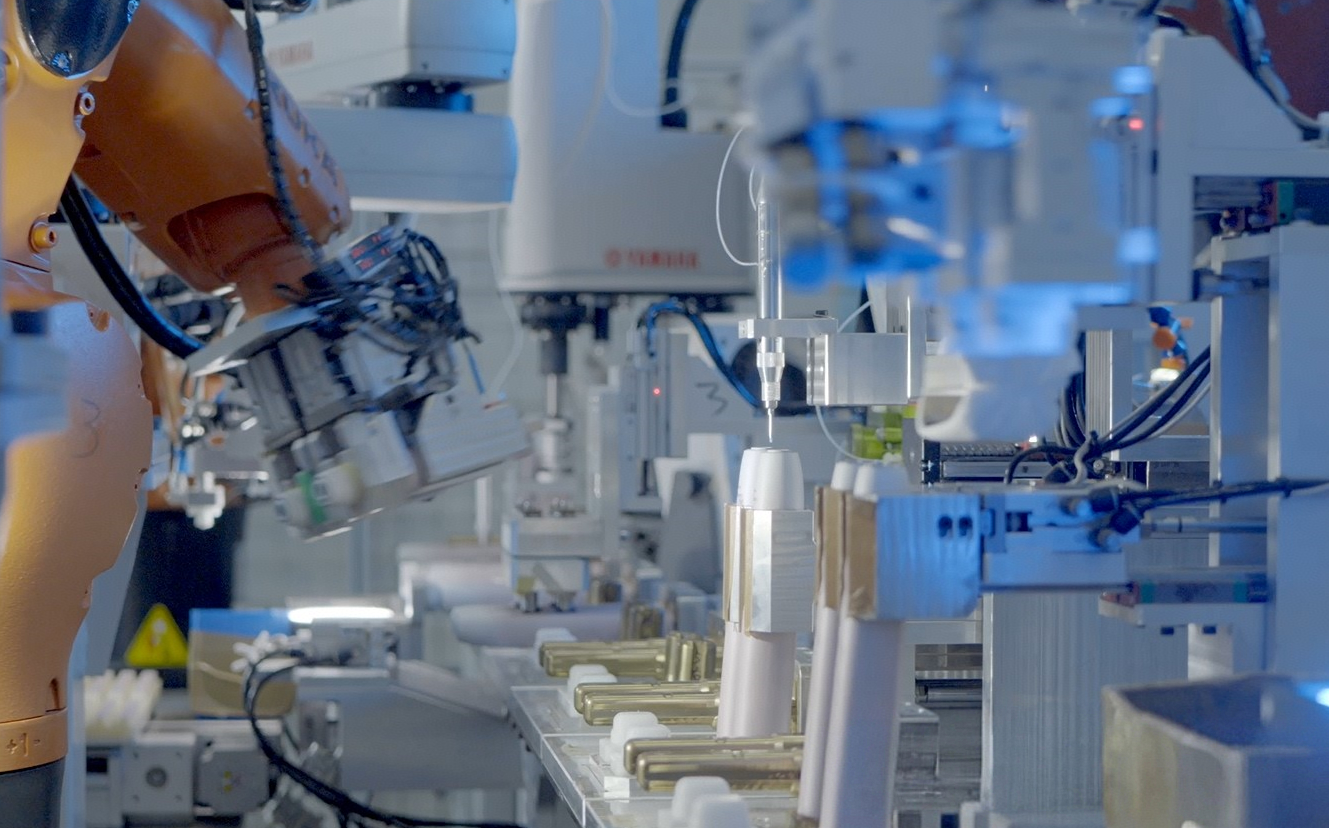
As a world-leading one-stop integrated injection molding solution supplier, Samudy provides tailor-made, cost-effective and high-precision injection molded products and services to numerous internationally renowned companies.
Revenue from the smartphones and wearables segment increased significantly by 51.2% year on year, thanks to several wireless earbuds brand customers and smart bracelet brand customers launching new product series and replenishing inventory in the market, driving significant growth in the Group's orders. Revenue from the business communication equipment segment increased substantially by 44.2% year on year, as brand customers, having completed product recalls last year, regrouped and launched new products during the Period with a favorable market response. The smart home segment rose 8.1% year on year, with demand remaining stable. Revenue from personal care brand customers returned to growth, increasing 18.2% year on year; revenue from medical consumables brand customers such as in vitro diagnostics, blood glucose monitoring and hemodialysis increased significantly by 38.6% year on year; however, orders from some smaller medical consumables customers fluctuated considerably, causing overall revenue of the medical and personal care segment to decrease 8.5% year on year. Although revenue from the e-vaporizer segment decreased 7.1% year on year, based on customers' full-year order demand, revenue from this segment is expected to grow steadily.
Injection molding component manufacturing business (approximately 73.3% of total revenue)
Revenue of the injection molding component manufacturing business segment was approximately HK$738.3 million (first half of 2023: HK$592.7 million), up 24.6% year on year. In the first half of 2024, the Group's injection molding business had full order books, and with higher capacity utilization, offsetting part of the initial development investment in new products, the gross margin of the injection molding business increased 1.0 percentage point to 21.7% (first half of 2023: 20.7%). The Group expects global inflation to continue to improve, with consumer sentiment expected to rebound more significantly in the second half of the year. Together with more active order demand from customers and a certain number of new projects entering mass production, gross margin is expected to continue to improve.
Mold making business (approximately 26.7% of total revenue)
In the first half of 2024, revenue from external customers of the mold making business was approximately HK$268.9 million, up approximately 2.1% from approximately HK$263.2 million in the same period last year. The automobile industry continued to recover, and with the rebound of high-end consumer electronics, personal care and other industries, brand owners re-deployed new product launches and replenished inventory. The Group's mold demand has recovered since the end of 2023 and has maintained steady growth. Given the long production cycle of molds, segment revenue growth will gradually materialize. In recent years, the Group's Industry 4.0 strategy has achieved results, significantly improving production efficiency and market competitiveness. During the Period, segment gross margin rose 4.3 percentage points to 33.5% (first half of 2023: 29.2%).


 Business Scope
 Component Solutions