Samudy Precision Tool Co Ltd
Samudy Holdings Limited
Announces2024Full-Year Results
* * *
Revenue Reached23.6Hundred Million HKD Profit Reached2.6Hundred Million HKD
Final Dividend8.8HKcents SpecialDividend10HKcents Full YearPayout Ratio Reached72.6%
Ongoing Customer Diversification China+Dual-Site Capacity Expansion in Vietnam to Seize Opportunities
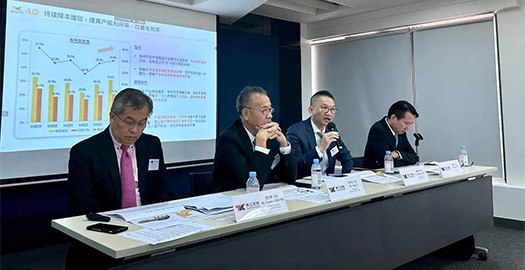
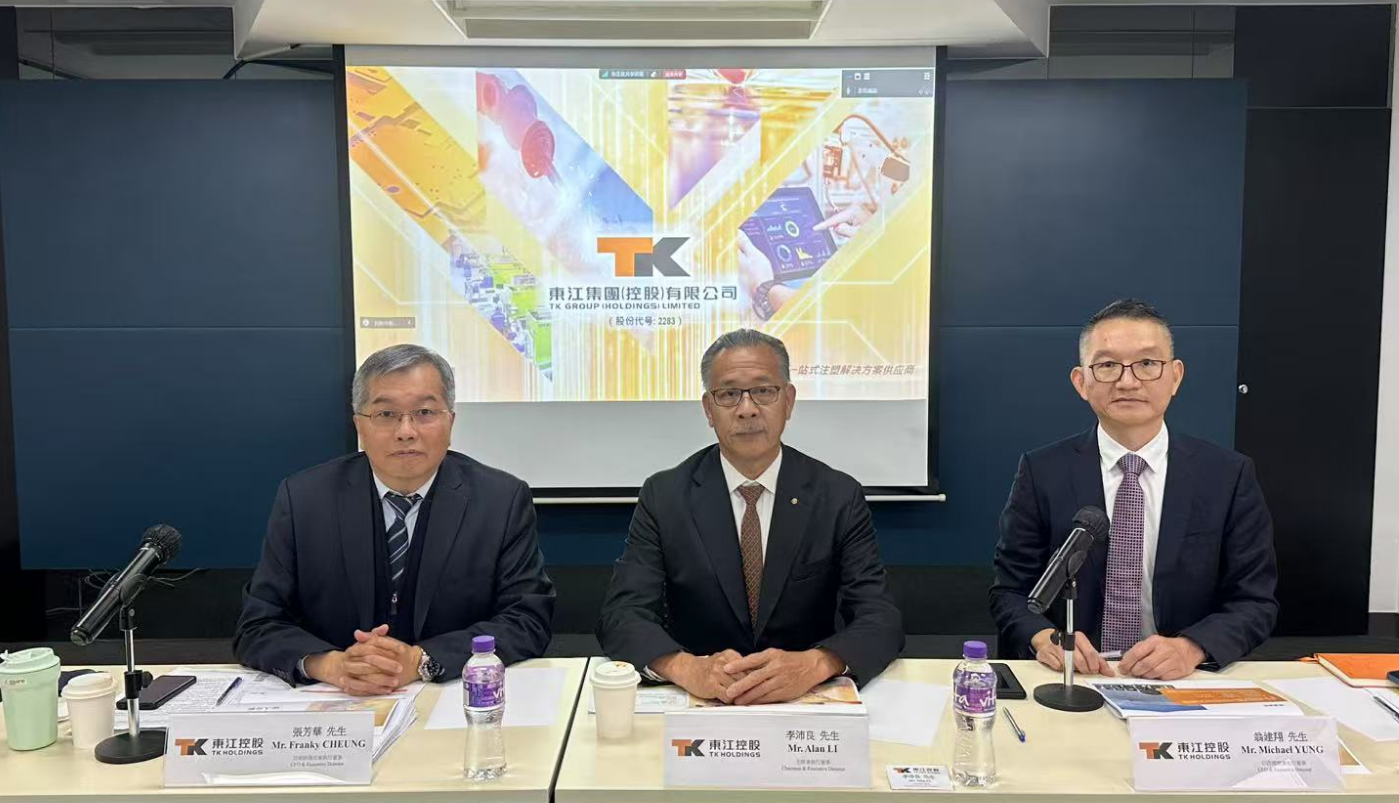
One of the World's Leading One-Stop Injection Molding Solution Suppliers — Samudy Holdings Limited (“Samudy” or the “Group”), on March 18, announced its full-year results for the year endedDecember 31, 2024 (the “Year”).
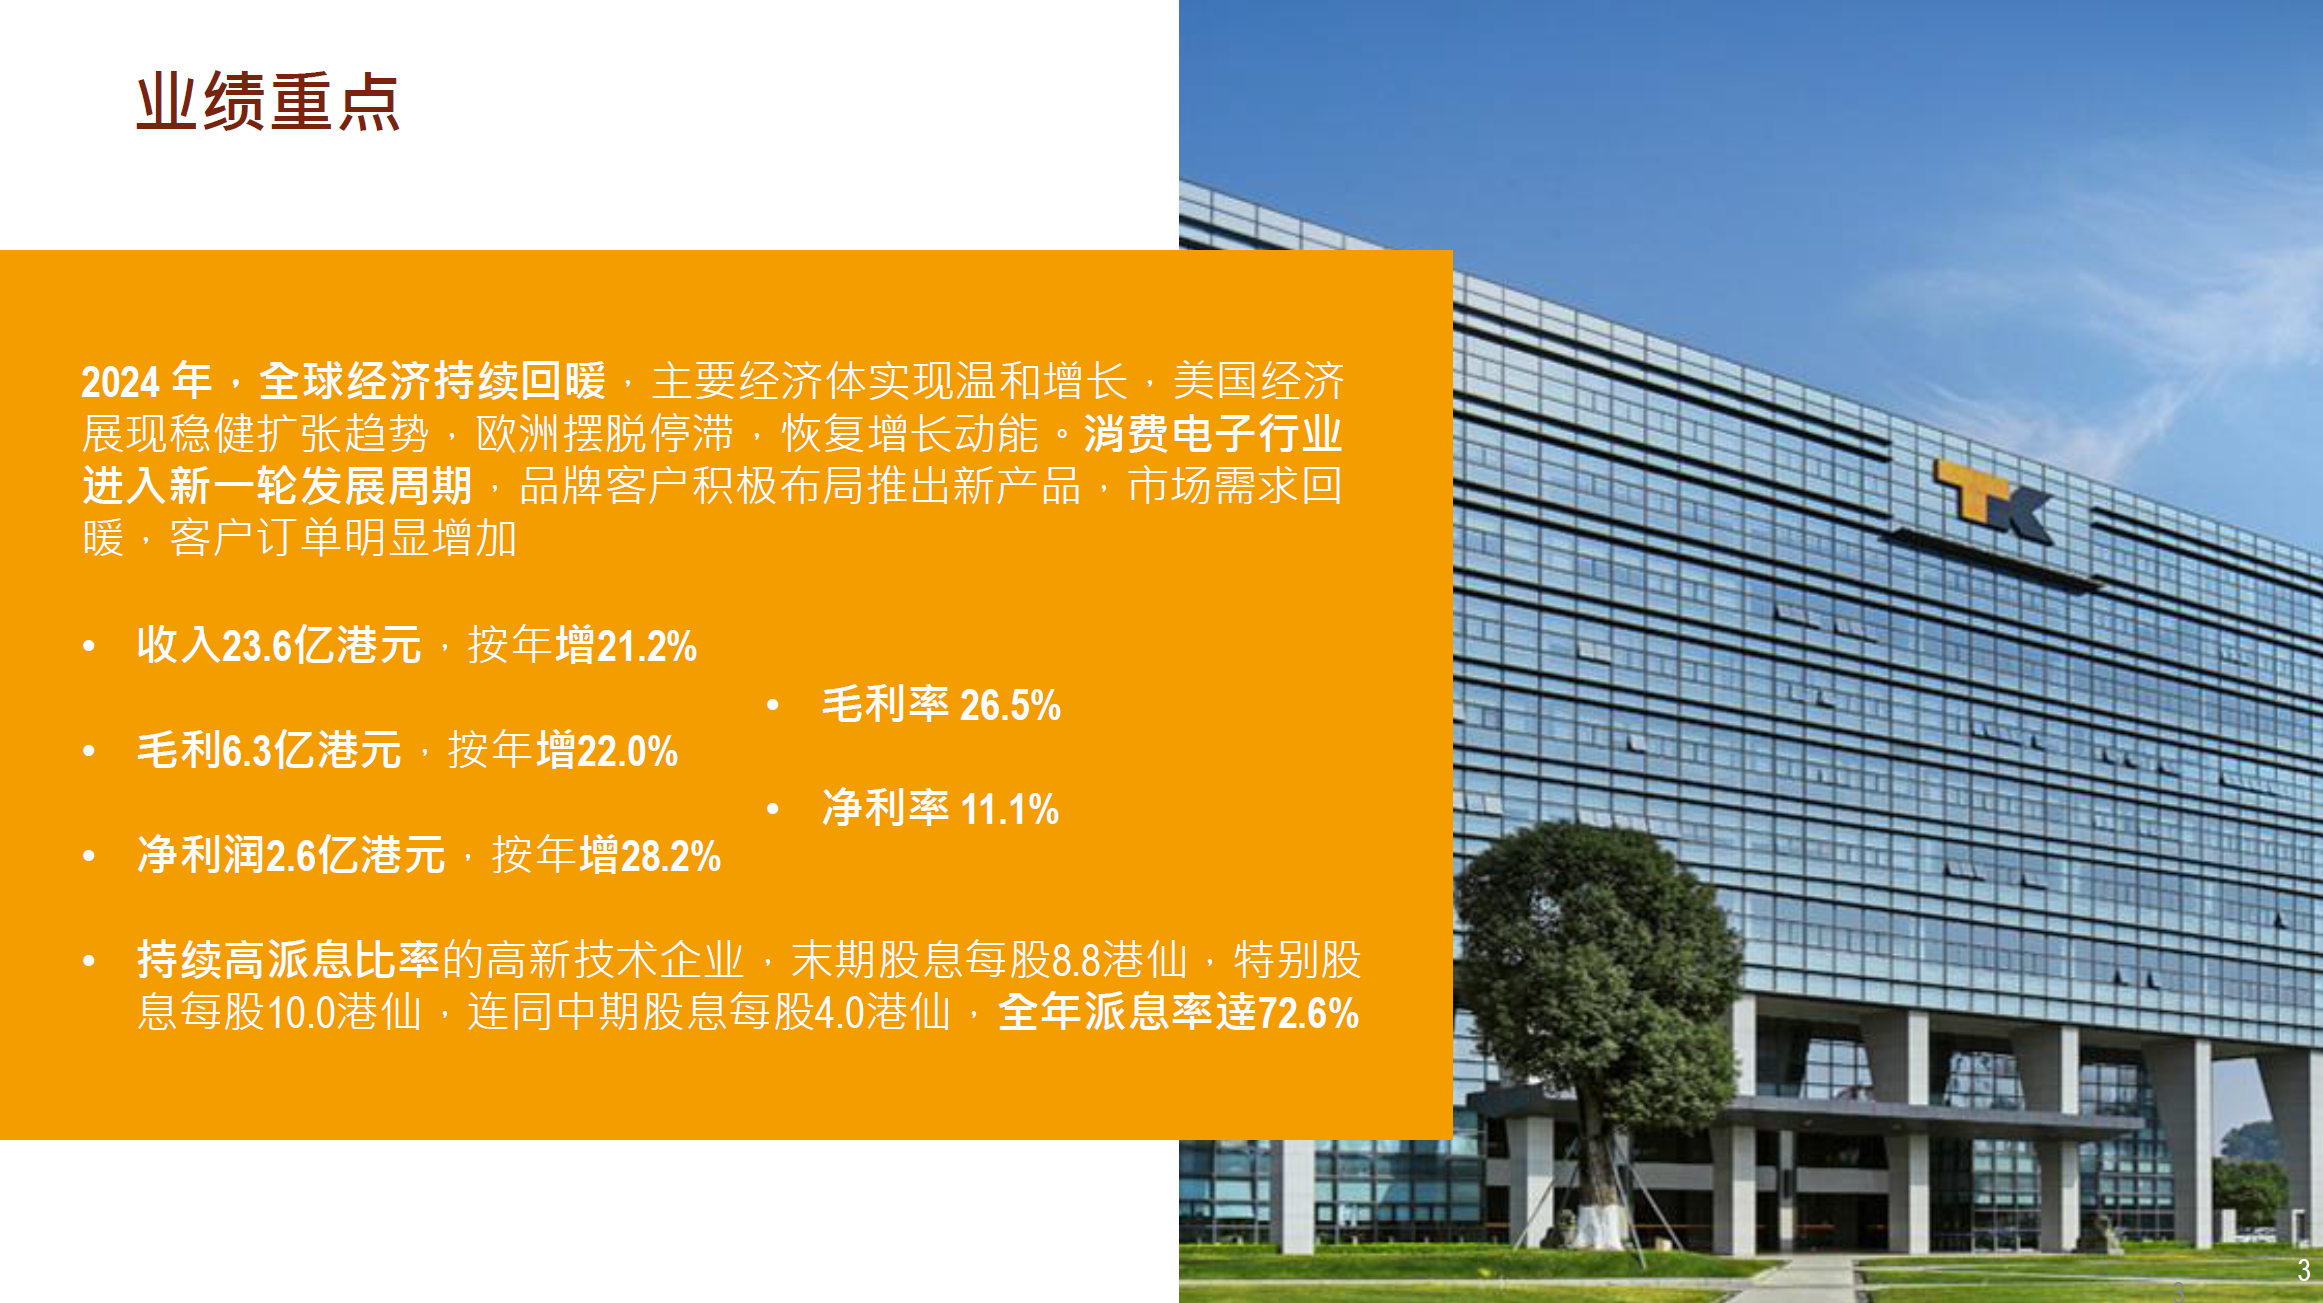
In 2024, the global economy continued to recover, with major economies achieving moderate growth. Global inflationary pressures eased further, and most countries entered rate-cutting cycles, lifting consumer confidence. The consumer electronics industry entered a new development cycle, with brand customers actively planning to launch new products, and customer orders increased significantly. The Group's2024full-year revenue reached2,358.3million HKD (2023: 1,945.7million HKD), up21.2% year on year. The mold-making business continued its steady growth, up12.7%, while the injection molded component manufacturing business rebounded significantly, growing25.2% year on year, with the mobile phone and wearable devices segment and the commercial communications equipment segment performing particularly well.
In 2024, as new products entered mass production, order volumes rebounded and capacity utilization improved significantly. The Group continued to optimize production processes and enhance management efficiency, with cost-reduction and efficiency-improvement measures continuing to deliver results. During the year, the Group's gross profit rose by22.0%to625.8million HKD (2023: 512.8million HKD). Profit rose substantially year on year, up28.2%, reaching261.9million HKD (2023: 204.2million HKD). Net margin increased by0.6percentage points to11.1% (2023: 10.5%), and basic earnings per share were0.32HKD (2023: 0.25HKD), up28.0%.
The Board has resolved to recommend, for the year endedDecember 31, 2024, a final dividend of8.8HK cents per share and a special dividend of10HK cents per share. Together with the interim dividend of4.0HK cents per share already paid, total dividends for the full year reached22.8HK cents per share, with the payout ratio increasing to72.6%.
Outlook
Looking ahead to2025, the global economic environment is full of opportunities and challenges. The rapid development of artificial intelligence is accelerating the integration of consumer electronics with technological innovation, speeding up industry growth. Together with the Chinese government's subsidy policy for new electronic product purchases, the consumer electronics industry is seeing a recovery in business sentiment, and brands are actively preparing to launch new products. Management is optimistic about the business outlook.
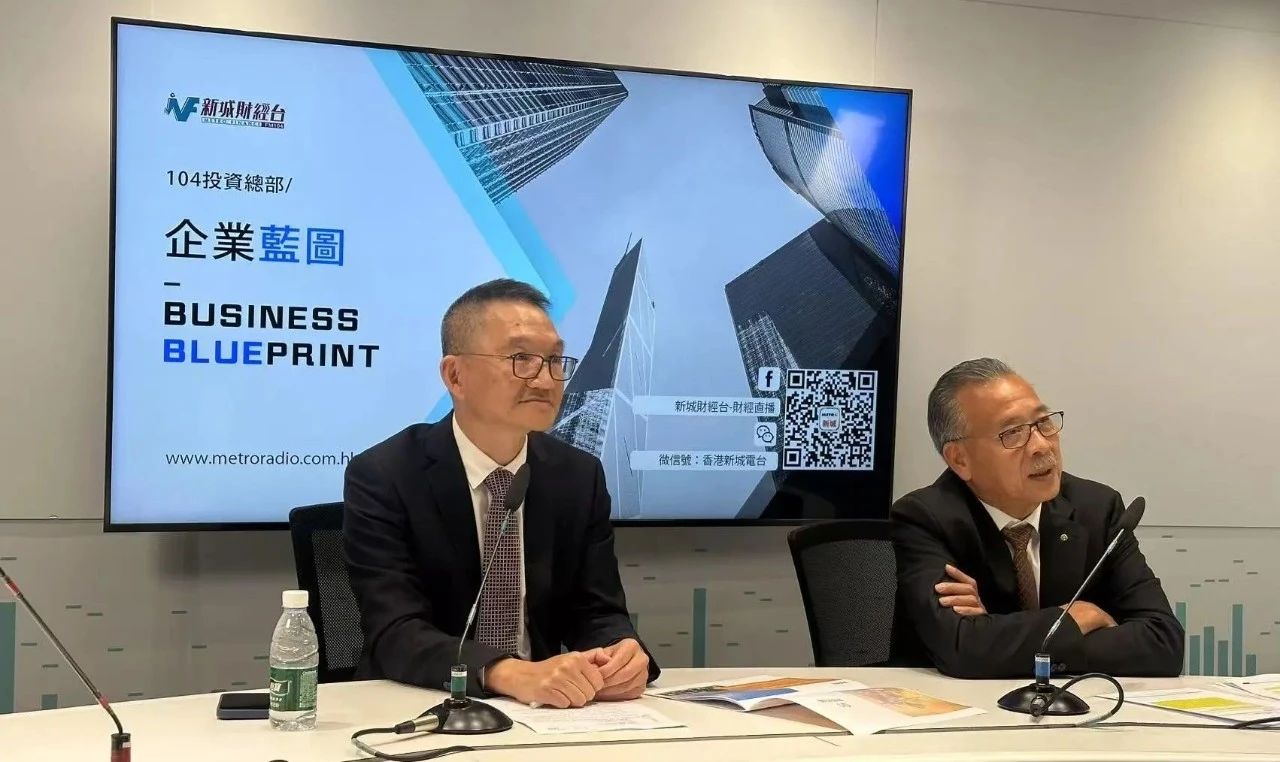
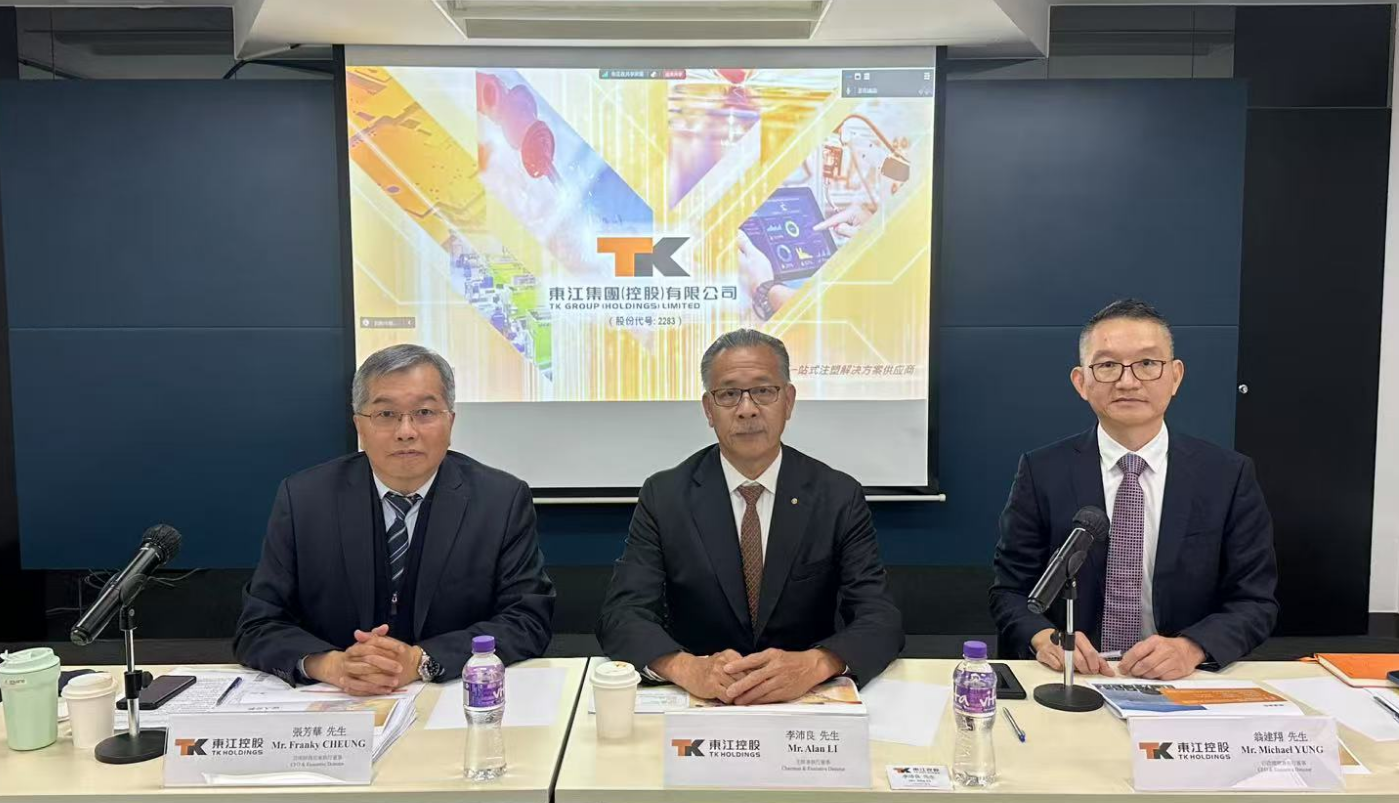
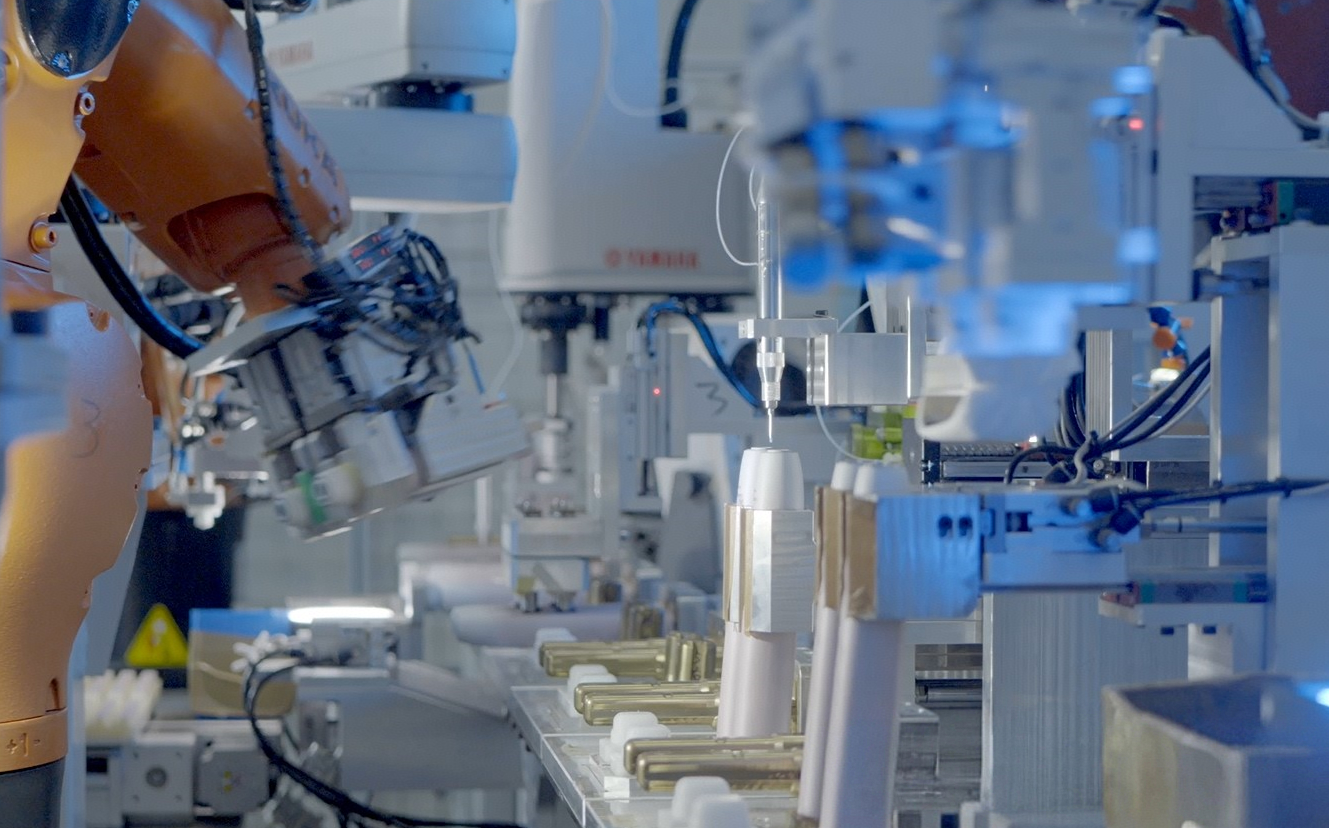
Mr. Li Peiliang, Chairman of Samudysaid: “The Group has closely followed industry transformation trends and successfully established an overseas production base in Vietnam, forming a ‘China+Vietnam’ dual-production-site layout to address market volatility and enhance supply chain resilience. The Group plans to quadruple the production area of its Vietnam plant, replicate the premium injection molding capabilities of its China production base at the Vietnam plant, and provide mold maintenance and repair services to safeguard the speed and efficiency of large-scale production. The Group also plans to upgrade its domestic production bases to comprehensively enhance manufacturing capabilities and production efficiency. The Suzhou plant will expand capacity to further improve production efficiency and embrace new opportunities in East China. The Shenzhen Guangming District headquarters will increase investment, on the one hand expanding its fully automated cleanroom production workshop for medical consumables, and on the other hand enhancing precision mold manufacturing capabilities and precision, staying at the technological forefront of the mold industry with solid strength and providing customers with highly reliable, groundbreaking plastic product solutions.” He further said: “The Group actively responds to the national new quality productive forces strategy, leveraging technologies such as a data middle platform and artificial intelligence to optimize process management, ensure the continuous refinement of production processes, and enhance the stability of high-precision production. In addition, through deepening Industry4.0 applications to raise the level of digitalization and intelligence in production processes, further improving production efficiency and achieving cost reduction and efficiency gains.”
Mr. Weng Jianxiang, Executive Director and Chief Executive Officer of Samudyadded: “The Group is committed to technological breakthroughs and innovation, continuously improving mold and injection molding related processes and providing differentiated and comprehensive solutions, including the integration of silicone and traditional injection molding technologies and direct pad printing processes, to create diversified, high-end plastic shell products for domestic and international brand customers, lead market trends and drive the iteration of end products. The Group is deepening strategic cooperation with consumer electronics brands, increasing investment in new product development, and actively expanding its market presence. The Group has successfully entered the supply chain of a leading metaverse industry enterprise, providing all-round support for customers' R&D from mold manufacturing to product design in developingARglasses and helping new products reach the market.” He further added: “To further optimize the industrial layout and enhance competitive advantages, management is actively exploring various possibilities for extending the industrial value chain and keeping a close eye on potential M&A opportunities, with a view to providing customers with more comprehensive one-stop solutions through vertical integration of the industry chain.”
2024Business Review
As one of the world's leading one-stop integrated injection molding solution suppliers, Samudy provides tailored, cost-effective and high-precision injection molded products and services to numerous internationally renowned enterprises.
Revenue from the mobile phone and wearable devices segment increased significantly year on year, by41.7%, mainly benefiting from several wireless earbuds and smart wristband brand customers launching new product series, which drove a marked increase in the Group's orders.Revenue from the commercial communications equipment segment increased substantially year on year, by35.3%, mainly because brand customers completed product recalls in2023 and successively launched new-generation products in2024 with a favorable market response. Meanwhile, the smart home segment performed steadily, with revenue up4.7% year on year. During the year, in addition to serving the two leading global brand customers in the industry, the Group newly developed a globally renowned high-end home goods brand customer. Revenue from the medical and personal care segment increased year on year by0.2%. Among these,revenue from personal care brand customers rebounded, increasing significantly year on year by34.5%, mainly to replenish market inventory. Revenue from domestic medical consumables brand customers, including in-vitro diagnostics and hemodialysis, also recorded significant growth However,some overseas medical customer orders declined due to the U.S. tariffs imposed at the beginning of last year, offsetting part of the growth from the domestic segment.In addition, revenue from the electronic atomizer segment increased year on year by10.5%, and the Group will further increase production capacity in response to customer demand.
Injection Molded Component Manufacturing Business (accounting for approximately70.4%)
Revenue from the injection molded component manufacturing segment was approximately1,660.1million HKD (2023: 1,326.1million HKD), up25.2% year on year. In 2024, the Group's injection molding business grew markedly. Orders from most customers rebounded after last year's inventory destocking, and with several new products entering mass production, capacity utilization improved significantly, effectively offsetting part of the impact of early-stage development investment in new products and driving up the gross margin of the injection molding business by0.7percentage points to22.1% (2023: 21.4%). The Group expects that in2025 global inflationary pressures will continue to ease and consumer sentiment is expected to keep improving. Together with increased demand from new customers and new projects successively entering mass production, capacity utilization will continue to improve, further enhancing the gross margin.
Mold-Making Business (accounting for approximately29.6%)
In 2024, revenue from external customers in the mold-making business was approximately698.2million HKD, compared with approximately619.6million HKD in the same period last year, up approximately12.7%. The Group's mold demand has grown steadily since the2023year-end recovery, maintaining stable growth. Given the relatively long mold production cycle, the segment's revenue growth will gradually materialize. The Group's Industry4.0strategy implemented in recent years has achieved remarkable results, maintaining sound production efficiency and market competitiveness. In2024, the gross margin of the mold-making segment remained at a high level of37.0% (2023: 37.0%).


 Business Scope
 Component Solutions