Announces 2022 Interim Results
* * *
Revenue exceeds HK$970 million; profit reaches HK$58.5 million Interim dividend of 2.8 HK cents Payout ratio of 39.9%
Orders on hand reach HK$1.00 billion; diversified product portfolio
Continuing to advance the five-year doubling plan for injection molding business sales
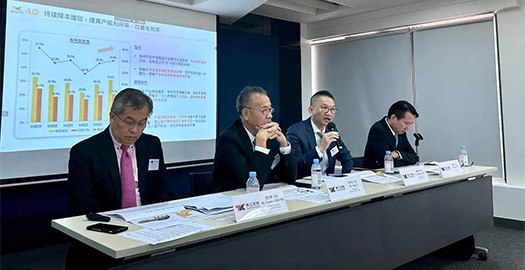
One of the world's leading one-stop injection molding solution suppliers — Samudy Holdings Limited ("Samudy" or the "Group"), today announced its interim results for the six months ended June 30, 2022 (the "Period").
In the first half of 2022, the pandemic caused by new variants, the international situation including China-US relations and the Russia-Ukraine war, and global inflation expectations dragged down the pace of global economic recovery, seriously affecting customer order volumes. In addition, the continued semiconductor shortage hindered normal production plans, and the Group's performance was also affected. In the first half of 2022, the Group's revenue was HK$969.2 million, down 5.1% from the same period last year, of which the mold making business fell 32.4% as automotive supply chains were disrupted, while the injection molding component manufacturing business recorded 10.2% growth.
With the semiconductor shortage unresolved, major automobile manufacturers and electronics makers reduced production. In addition, after Russia officially launched military action against Ukraine in the first half of the year, global markets were thrown into turmoil, energy and commodity prices rose rapidly, pushing production costs continuously higher and further fueling global inflation. Economic volatility coupled with high inflation expectations made consumer electronics customers more conservative. Customers frequently adjusted orders and delivery schedules, and the Group had to adjust its normal production scheduling accordingly, which in turn affected the Group's production efficiency and gross margin. The Group's gross profit fell 25.3% to HK$180.9 million (first half of 2021: HK$242.3 million). Gross margin fell 5.0 percentage points to 18.7% (first half of 2021: 23.7%). The Group recorded a profit attributable to owners of the Company of HK$58.5 million, down approximately 49.3% from the same period last year. Net margin fell 5.3 percentage points to 6.0% (first half of 2021: 11.3%), and basic earnings per share were 7.0 HK cents, down 49.6% year on year.
Based on a sound cash flow position, the Board has resolved to recommend an interim dividend of 2.8 HK cents per share for the six months ended June 30, 2022, representing a payout ratio of 39.9%.
Outlook
In the second half of 2022, global inflation is expected to remain high, putting pressure on economic growth in the second half of the year. However, the Group believes that the overall business environment in the second half will be less volatile than in the first half, which is conducive to normal development. Facing various challenges in the macro environment, the Group will continue to forge ahead, implementing various cost control measures, promoting process optimization and automation, and organizational agility to improve operating efficiency. At the same time, leveraging its own advantages, the Group is actively extending the value chain, enhancing overall competitiveness, developing more customer sources, maintaining the competitive advantage of customer diversification, laying the foundation for long-term steady business development, and striving to maximize the interests of customers and shareholders.
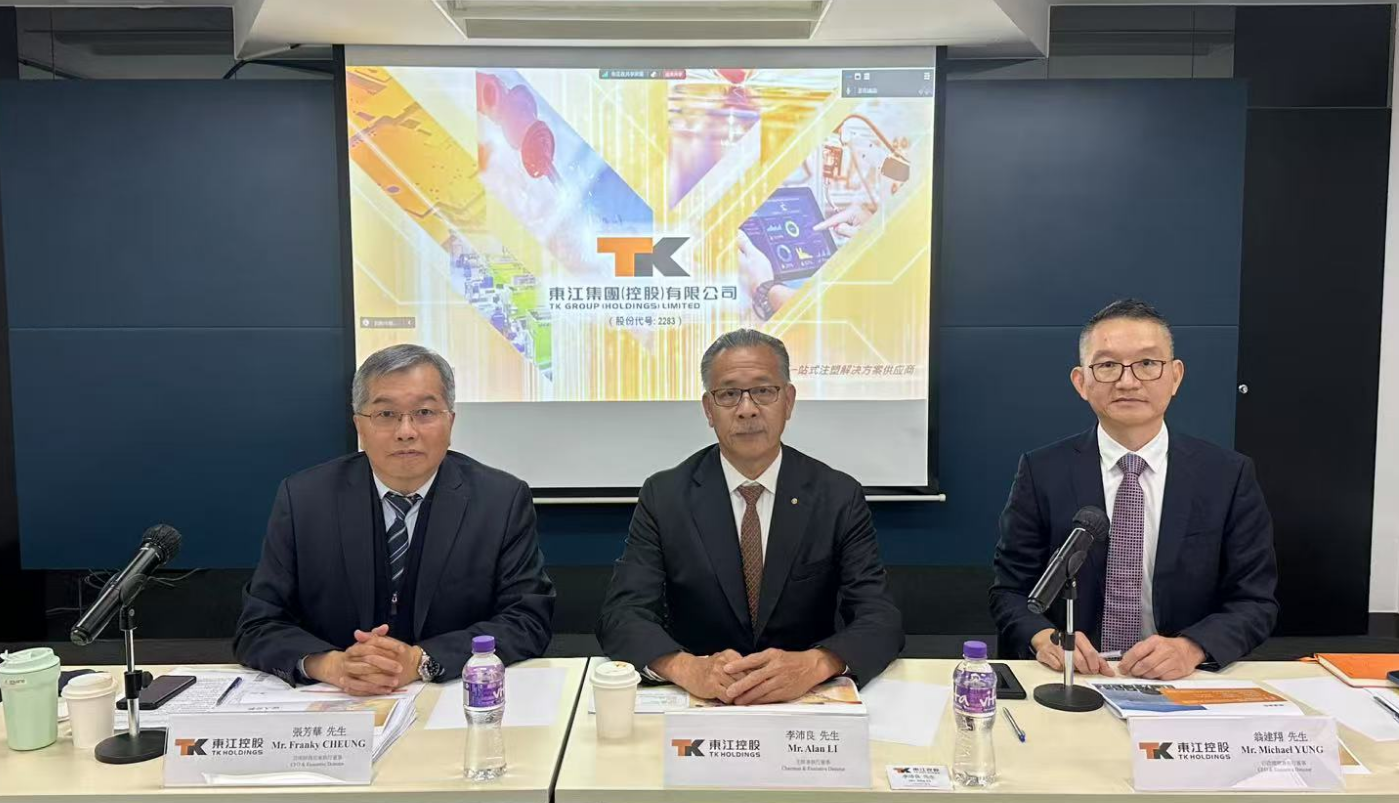
Mr. Li Peiliang, Chairman of Samudy, said: "The Group remains optimistic about the five-year doubling development plan for injection molding segment business sales. As for the mold business segment, the Group will vigorously develop the precision mold business. Samudy possesses the production capability for MT1 molds of the highest precision and will invest more resources to upgrade its technology based on the current precision level. At present, the precision of the Group's precision molds has gained favor and attention from mainland Chinese customers, laying a solid foundation for entering the mainland market in the future." He further noted: "The Group plans to commence the second phase of investment in its Vietnam production base in the second half of 2022. Expanding production capacity will help develop new customers from Southeast Asia, Europe and the United States."
Mr. Weng Jianxiang, CEO of Samudy, added: "The Group has been developing new products integrating silicone and traditional injection molding technology to provide customers with more diversified product designs. Given the growing customer demand for silicone products, the Group will lease a new plant in Huizhou in 2022 to further integrate production lines and improve production capacity and efficiency. The Group holds strong advantages in producing high-tech-feel product housings and has been in contact with several industry giants to develop new products related to the metaverse. In addition, management has always maintained a positive attitude toward M&A plans and has never stopped searching for suitable targets with development potential. Apart from considering acquiring peers, the Group also seizes opportunities to participate in the development of entirely new fields, keeping pace with the times to maintain long-term competitive advantages."
Business Review for the First Half of 2022
As a world-leading one-stop integrated injection molding solution supplier, Samudy provides tailor-made, cost-effective and high-precision injection molded products and services to numerous internationally renowned companies. During the Period under review, the smartphones and wearables, medical and personal care, and business communication equipment segments maintained steady growth, while the smart home and e-vaporizer segments delivered outstanding performance.
Revenue from the smartphones and wearables and medical and personal care segments maintained steady growth, increasing 2.0% and 1.1% year on year respectively. During the Period, demand for products from wireless earbuds brand customers and smartphone protective case brand customers continued to grow, with innovative product solutions integrating silicone playing a notable role. The Group newly developed multiple medical customers at home and abroad, effectively compensating for the short-term reduction in product orders from personal care brand customers caused by insufficient semiconductor supply. The Group is dedicated to serving the world's two leading smart home brand customers. Customers had multiple products in mass production during the Period with full order books, driving smart home segment revenue up 25.3% year on year. Thanks to its long-term and stable cooperation with business communication equipment customers, the Group remains the main supplier to customers after their transformation. Revenue from this segment rose 13.7% year on year, with satisfactory sales of new products. In addition, the overseas e-vaporizer market is booming. The Group mainly serves overseas brand customers, and its technology is recognized by customers. Business continues to develop, with revenue up 57.4% year on year.
Injection molding component manufacturing business (approximately 74.5% of total revenue)
Revenue of the injection molding component manufacturing business was approximately HK$722.0 million, up 10.2% from the same period last year. In the first half of 2022, the gross margin of the injection molding component manufacturing business fell to 17.3% (first half of 2021: 20.5%), mainly because customers frequently adjusted orders, production scheduling adjustments reduced production efficiency, and the Group adopted a more proactive business strategy, increasing investment in self-funded molds. The Group expects the semiconductor shortage to ease in the second half of the year, with order stability improving and gross margin expected to improve accordingly, achieving long-term sustainable development of the injection molding business.
Mold making business (approximately 25.5% of total revenue)
In the first half of 2022, revenue from external customers of the mold making business was approximately HK$247.2 million, down approximately 32.4% from approximately HK$365.5 million in the same period last year. Considering factors such as the supply shortage of semiconductors and component shortages, automobile manufacturers were forced to lower production targets, which affected order demand for the Group's standard molds and led to increased idle time of production equipment during the Period. Coupled with the depreciation pressure of the euro, segment gross margin fell 7.0 percentage points to 22.6%. In an increasingly competitive market environment, the Group is improving the profit margin of standard molds through cost reduction and efficiency improvement, while actively developing new customers and new projects for precision molds, deepening presence in the medical, consumer electronics and packaging industries, and exploring top-tier customers in related industries. The Group is continuously improving the precision of its precision molds, and its excellent technical quality is welcomed and sought after by mainland Chinese customers.


 Business Scope
 Component Solutions