Announces 2021 Annual Results
* * *
Revenue reaches HK$2.4 billion; profit exceeds HK$280 million, up 34.7% year on year; final dividend of 8.6 HK cents
Orders on hand reach HK$920 million; strong growth across multiple segments
Continuing to expand the domestic market in 2022
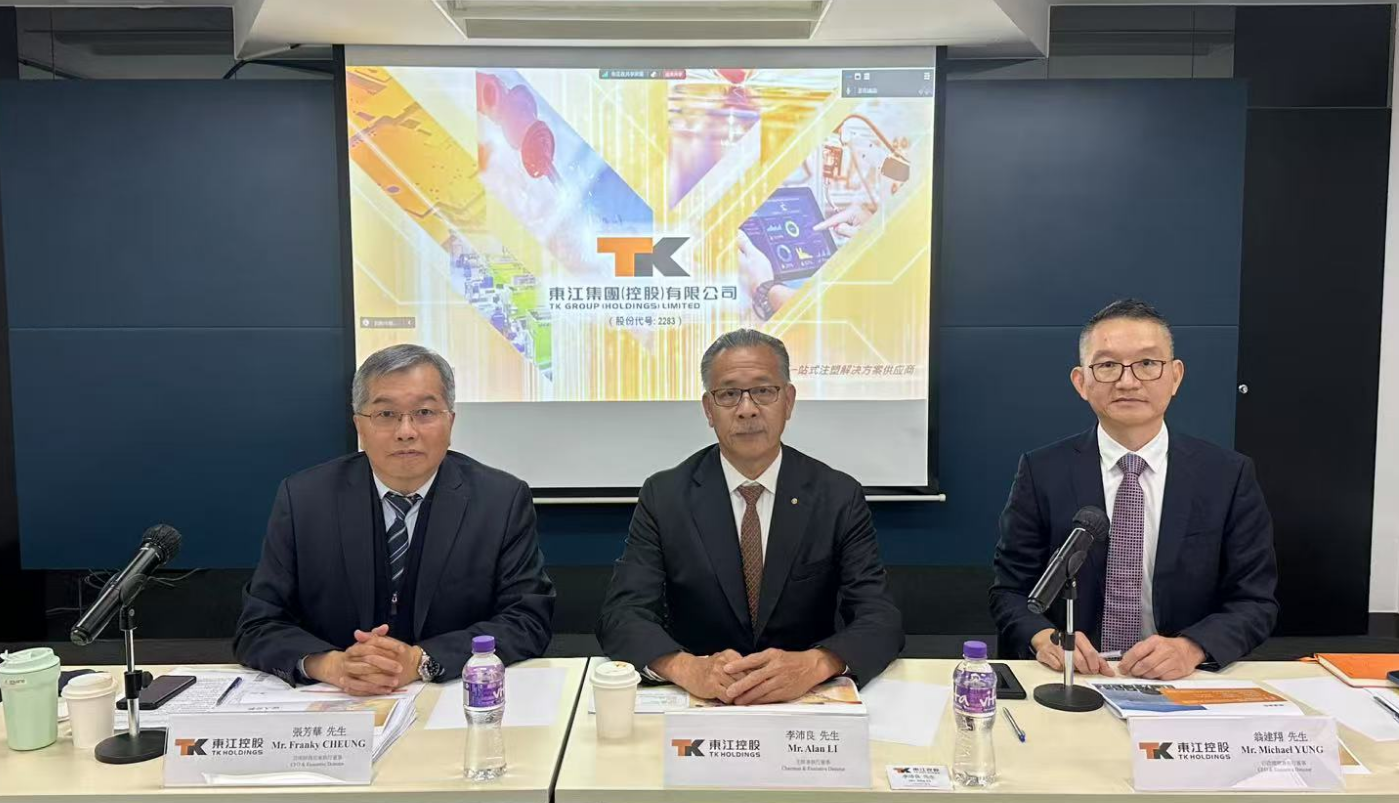
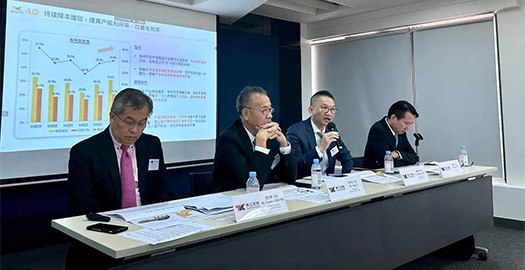
[March 25, 2022 – Hong Kong] One of the world's leading one-stop injection molding solution suppliers — Samudy Holdings Limited ("Samudy" or the "Group"), today announced its annual results for the year ended December 31, 2021 (the "Year").
In 2021, the global economy recovered gradually from the low point caused by the COVID-19 pandemic in the previous year. European and American economies were successively reopened, and countries generally implemented large-scale relief and stimulus measures to boost their economies and stimulate consumer sentiment. In addition, as Samudy's main production capacity is located in China, thanks to China's relatively successful pandemic prevention policies, the Group's production remained stable. In 2021, the Group's revenue recovered to the 2019 level from the impact of the pandemic. The Group's full-year revenue for 2021 reached HK$2,404.4 million (2020: HK$2,033.4 million), up 18.2% year on year.
However, the impact of new virus variants continued in 2021, preventing the supply chain from fully recovering, and with the imbalance between supply and demand, raw material prices kept climbing. In addition, the global semiconductor shortage significantly affected the production plans and order demand of some customers, and customers' frequent order adjustments also affected production efficiency. During the Year, the Group's gross profit rose 6.9% to HK$569.2 million (2020: HK$532.6 million). Gross margin fell 2.5 percentage points to 23.7% (2020: 26.2%). However, with the Group's effective control of selling and administrative expenses, profit attributable to owners of the Company increased significantly by 34.7% year on year to HK$282.4 million (2020: HK$209.7 million). Net margin increased 1.4 percentage points to 11.7% (2020: 10.3%), and basic earnings per share were HK$0.34 (2020: HK$0.25), up 36.0% year on year.
The Board has resolved to recommend a final dividend of 8.6 HK cents per share for the year ended December 31, 2021. Together with the interim dividend of 5.4 HK cents per share already paid, the payout ratio reached 41.3%.
Outlook
The COVID-19 pandemic has lasted for more than two years, affecting raw material supply, logistics, production and even the global supply chain ecosystem. In addition, trade measures and geopolitical and economic conflicts between countries still pose certain obstacles to the full recovery of the economy. Facing an uncontrollable macro economy, the Group's customer industry diversification strategy has become more advantageous, effectively spreading business risks across different economic cycles to face the ever-changing market. In fact, the Group's various business segments have recovered to varying degrees, and newly developed emerging industries have also brought growth momentum. As of December 31, 2021, the Group's orders on hand reached HK$918.3 million. Samudy is confident in maintaining the competitive advantage of customer diversification to embrace the changes and challenges of the new year and continue to create value for customers and shareholders.
Mr. Li Peiliang, Chairman of Samudy, said: "In 2020, the Group set its first five-year plan, establishing a goal of doubling sales for the injection molding business in five years. We are pragmatically and continuously moving toward the expected goal, and have launched a series of internal reform policies to promote the whole company working together to drive business growth." He further noted: "In November 2021, the Group established an injection molding production base in Vietnam and commenced the first phase of production. We plan to implement the second phase of production in the second half of 2022. Establishing a plant in Vietnam also helps the Group explore and develop new markets locally and in neighboring regions, preparing for long-term growth demand from the Southeast Asian supply chain and European and American markets."
Mr. Weng Jianxiang, Executive Director and CEO of Samudy, added: "We adopt a positive attitude toward M&A plans with development potential, striving to keep pace with the times and maintain the Group's competitive advantages in the industry. Over the past year, the Group invested in capacity expansion at its Huizhou production base and acquired Yagao Silicone Products Co Ltd to broaden its product lines. These initiatives have gradually yielded results, and the Group has successfully developed several promising new projects, providing further development space for the business. In the coming year, the Group will continue to invest in related projects and maintain a diversified business layout, building close relationships with industry leaders. On the one hand, we will continue to support long-term overseas customers in realizing their global market expansion plans; on the other hand, we will continue to expand the domestic market, especially strong, industry-leading corporate brands, striving to help customers seize the opportunities of the national dual circulation policy and enter the international market."
Business Review for 2021
As a world-leading one-stop integrated injection molding solution supplier, Samudy provides tailor-made, cost-effective and high-precision injection molded products and services to numerous internationally renowned companies. During the Year under review, the downstream smartphones and wearables, business communication equipment, smart home and other segments achieved strong growth, and the new e-vaporizer segment also delivered outstanding performance.
Revenue from the smartphones and wearables segment increased 11.7% year on year, thanks to the popularity of products from wireless earbuds brand customers and smartphone protective case brand customers, driving significant growth in the Group's orders. Revenue from the smart home segment rose substantially by 51.1% year on year, benefiting from the stabilizing economies of European and American countries and the rapid recovery of consumer demand, with multiple products of the Group's two major brand customers entering mass production during the Year. Revenue from the medical and personal care segment decreased 4.6% year on year, mainly because personal care customers reduced orders temporarily as product output was affected by the semiconductor shortage. However, this has not affected the Group's strategic investment in this segment; the Group is actively developing well-known medical brand customers at home and abroad and remains optimistic about the long-term development of this segment. Revenue from the business communication equipment segment increased significantly by 70.5% year on year, as customers adjusted their supply chains and transferred part of their suppliers' production share to the Group, leading to a substantial increase in sales. Newly developed products from customers have been well received in the market, and under the latest supply chain portfolio, the Group remains the main supplier of customers' new products, with a stable outlook.
Injection molding component manufacturing business (approximately 70.6% of total revenue)
The overall revenue of the injection molding component manufacturing business was approximately HK$1,698.4 million (2020: HK$1,333.2 million), up 27.4% from the same period last year. The gross margin of the injection molding business fell to 22.2% (2020: 25.6%), mainly because raw material prices rose too quickly in the short term, making it difficult to fully pass on costs to customers in a short time. In addition, tight logistics and the semiconductor shortage hampered production scheduling, leading to lower production efficiency and lower machine utilization. The Group expects that with improved material supply and easing logistics difficulties, together with a certain number of new projects entering mass production, capacity utilization will improve and the gross margin will return to a healthy level.
Mold making business (approximately 29.4% of total revenue)
In 2021, the mold segment continued the good momentum of the second half of 2020. Customers actively launched new products, keeping mold demand stable. Revenue grew slightly by 0.8% to HK$706.0 million (2020: HK$700.2 million), and segment gross margin edged down 0.3 percentage points to 27.1% (2020: 27.4%). Facing market pressure, the Group will continue to improve its process technology, expand its mold product scope, deepen customer relationships, and provide high-quality mold and design solutions to maintain competitive advantages. China's domestic circulation economic policy provides opportunities in the domestic market. In addition to overseas export customers, the Group is actively developing new domestic customers and pursuing a customer diversification strategy.


 Business Scope
 Component Solutions