Announces 2021 Interim Results with Strong Rebound
* * *
Revenue reaches HK$1.02 billion; profit exceeds HK$115 million
Interim dividend of 5.4 HK cents Payout ratio of 39.1%
Orders on hand reach HK$1.07 billion
Strong growth across multiple segments
Further expanding domestic sales in the second half of the year
[August 16, 2021 – Hong Kong] One of the world's leading one-stop injection molding solution suppliers — Samudy Holdings Limited ("Samudy" or the "Group"), today announced its interim results for the six months ended June 30, 2021 (the "Period").
In the first half of 2021, the global economy continued its recovery amid volatility. As the COVID-19 pandemic was brought under control in European and American economies, related restrictive measures were gradually relaxed, economic activities gradually returned to normal, and consumer demand accelerated its recovery. China's production side largely returned to pre-pandemic output levels, and the Group's orders and production volume also recovered from the pandemic to levels similar to 2019. In the first half of 2021, the Group's revenue was HK$1,020.8 million (first half of 2020: HK$729.4 million), up 40.0% year on year.
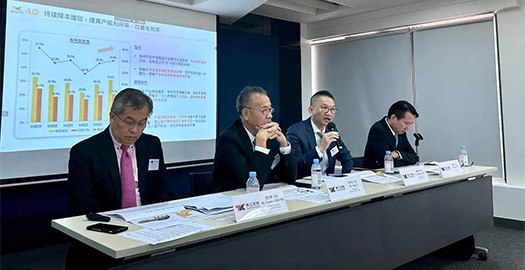
During the Period, thanks to full order books leading to higher capacity utilization compared with the same period last year, the Group's gross profit was HK$242.3 million (first half of 2020: HK$162.5 million), up 49.1% year on year, with gross margin up 1.4 percentage points to 23.7% (first half of 2020: 22.3%). Compared with the same period in 2019, the upfront costs of new products and raw material price fluctuations in the first half of 2021 inevitably dragged down overall gross margin performance. However, raw material price fluctuations eased after May, and with the shakedown period of new projects over, production efficiency will improve, and gross margin performance in the second half of the year is expected to continue to improve. The Group recorded a profit attributable to owners of the Company of HK$115.2 million (first half of 2020: HK$41.4 million), a substantial increase of 178.5% year on year, essentially on par with the same period in 2019. Net margin was 11.3% (first half of 2020: 5.7%), up 5.6 percentage points year on year, and basic earnings per share were 13.9 HK cents (first half of 2020: 5.0 HK cents).
The Board has resolved to recommend an interim dividend of 5.4 HK cents per share for the six months ended June 30, 2021, representing a payout ratio of 39.1%.
Outlook
As European and American countries gradually reopened following the easing of the pandemic, the global economy continued to rise. The Group expects economic growth to accelerate further in the second half of the year, driving consumer demand. In Asian countries with new COVID variants and rising case numbers, the pandemic remains a huge threat to economic growth. Facing the turbulent economic situation, management continues to respond with a prudent attitude. Long-term stable cash flow and a sound financial position lay a solid foundation for long-term business development, and the Group will break through difficulties and move forward steadily in the turbulent market.
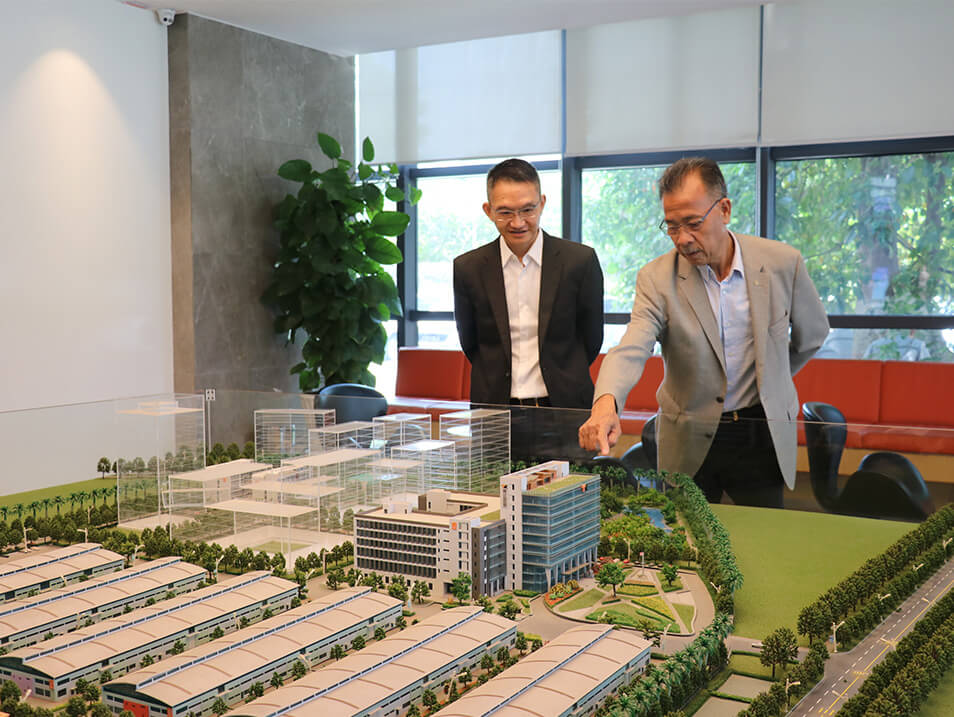
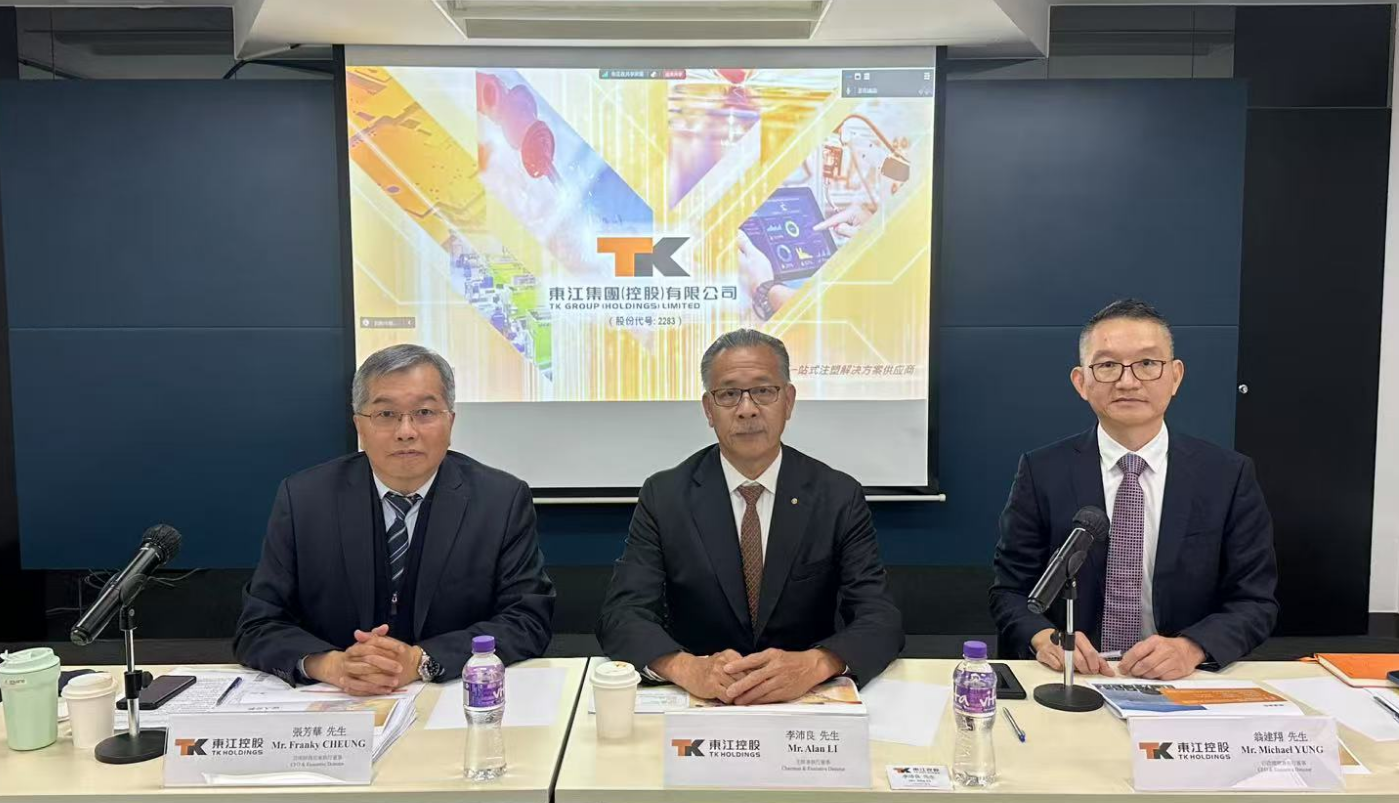
Mr. Li Peiliang, Chairman (right) and Mr. Weng Jianxiang, CEO (left) of Samudy
Mr. Li Peiliang, Chairman of Samudy, said: "Last year, the Group set its first five-year development plan, establishing a goal of doubling sales for the precision mold and injection molding businesses in five years. We are confident of achieving the expected goals as planned. As of June 30, 2021, the Group's orders on hand reached HK$1,065.0 million. The record-high orders on hand and the performance of multiple segments far exceeding 2019 levels attest to the attainability of the Group's five-year plan. With sufficient injection molding product orders plus the technical advantages of molds, the growth potential of the overall business in the future is believed to be enormous." He further noted: "The Group's overseas injection molding plant established in Vietnam is expected to commence mass production this year. Injection molding capacity in Southeast Asia will complement customer demand and build reserves for new projects in the long run."
Mr. Weng Jianxiang, CEO of Samudy, added: "The Group has been constantly searching for M&A targets. This year, we will focus on finding suitable targets within the supply chains of downstream customers, seizing business development opportunities and striving to expand the new territory of our business. Customer diversification has always been a strategy the Group adheres to. In the second half of the year, Samudy will continue to develop new customers and strive to provide quality products to brand customers. In addition, the Group continues to advance its internal growth and external expansion strategy. This year, we will further expand domestic sales to diversify geographic risks."
Business Review for the First Half of 2021
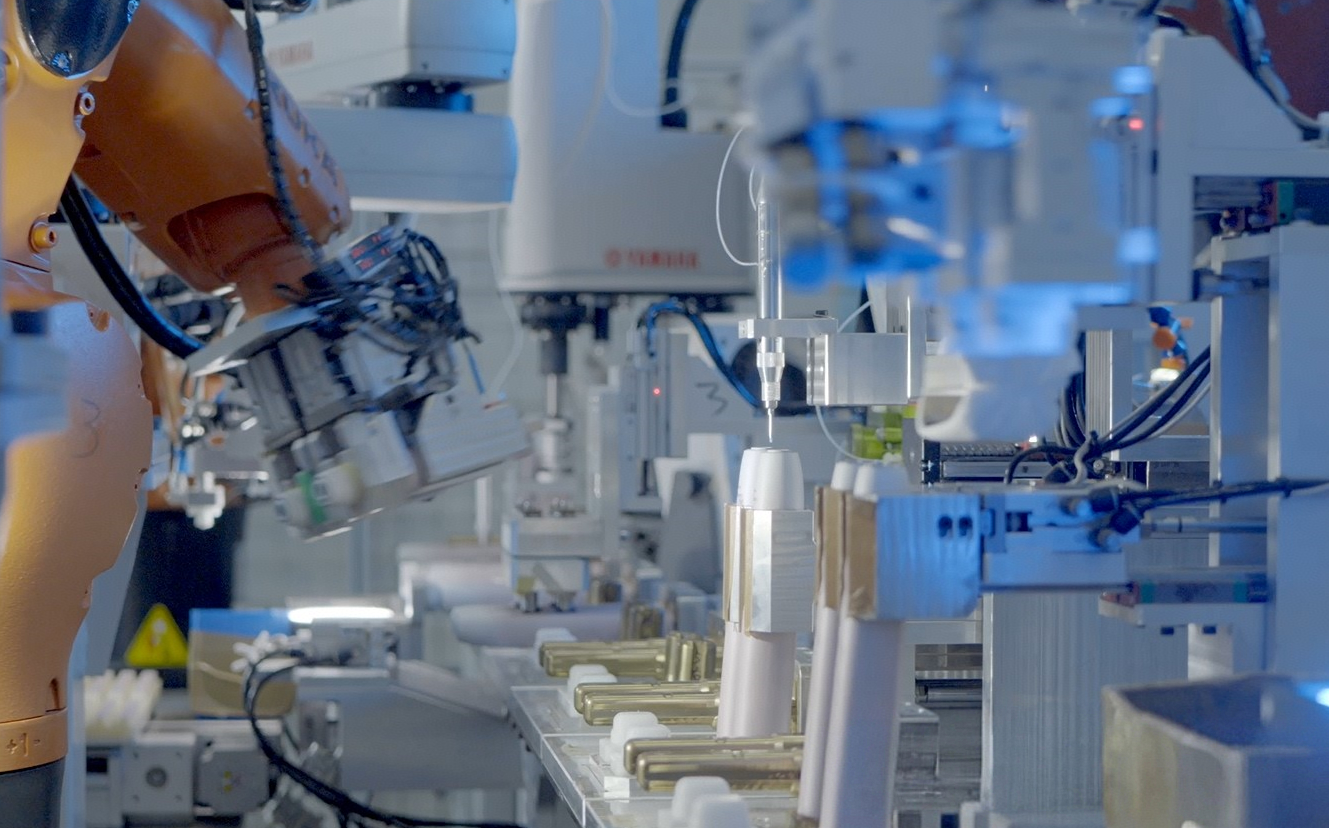
As a world-leading one-stop integrated injection molding solution supplier, Samudy provides tailor-made, cost-effective and high-precision injection molded products and services to numerous internationally renowned companies. During the Period under review, the smartphones and wearables, automotive, medical and personal care, smart home and business communication equipment segments recorded strong growth, and the new e-vaporizer segment also delivered outstanding performance.
Revenue from the smartphones and wearables segment increased 31.4% year on year and 16.0% compared with the same period in 2019, thanks to significant growth in orders from wireless earbuds brand customers and smartphone protective case brand customers. Demand in the medical and personal care segment has maintained steady growth, with revenue up 34.0% year on year. During the Period, the Group added multiple well-known medical brand customers at home and abroad, covering areas such as in vitro diagnostics, blood glucose monitoring and immunoassay, with related injection molded components to be produced in succession in the second half of the year. Revenue from the smart home segment increased substantially by 67.4% year on year and 12.8% compared with the same period in 2019, thanks to the commencement of new projects during the Period for a newly added leading North American smart home brand customer. Revenue from the business communication equipment segment rose 55.2% year on year. Although customers' traditional products are gradually saturating the market, customers' transformation strategies have been gradually implemented, with other commercial product lines being launched in succession, such as commercial earbud products launched in North America. Thanks to long-term and stable cooperation with customers, the Group remains the main supplier of customers' new products, with ample orders in the second half of the year and full-year sales expected to continue to rebound. After more than a year of efforts, revenue from the new e-vaporizer segment increased significantly, contributing notably to the Group, with revenue up 215.9% year on year.
Injection molding component manufacturing business (approximately 64.2% of total revenue)
The overall revenue of the injection molding component manufacturing segment was approximately HK$655.3 million (first half of 2020: HK$457.8 million), up 43.1% year on year. In the first half of 2021, machine idle time decreased, and the gross margin of the injection molding business increased 1.6 percentage points from approximately 18.9% in the same period last year to 20.5%. The Group expects that in the second half of the year, with a certain number of new projects entering stable mass production and sufficient orders on hand, capacity utilization will increase significantly and gross margin will improve accordingly.
Mold making business (approximately 35.8% of total revenue)
The Group's extra-large standard molds mainly target automotive components, with customers primarily being tier-one component suppliers producing automotive parts for European automobile brands such as Mercedes-Benz, BMW and Volkswagen. The precision mold production line mainly produces multi-cavity and high-efficiency precision molds, covering markets such as smart home, high-end consumer electronics including smartphones and wearables, business communication equipment, medical and personal care, complementing the downstream injection molding component manufacturing business to provide customers with better one-stop services.
In the first half of 2021, revenue of the mold making business was approximately HK$365.5 million, up approximately 34.6% from approximately HK$271.6 million in the same period last year. As international freight problems delayed last year's orders to be shipped in the first half of this year, mold segment revenue grew significantly year on year, and the gross margin of the mold making segment rose 1.7 percentage points to 29.6%.


 Business Scope
 Component Solutions